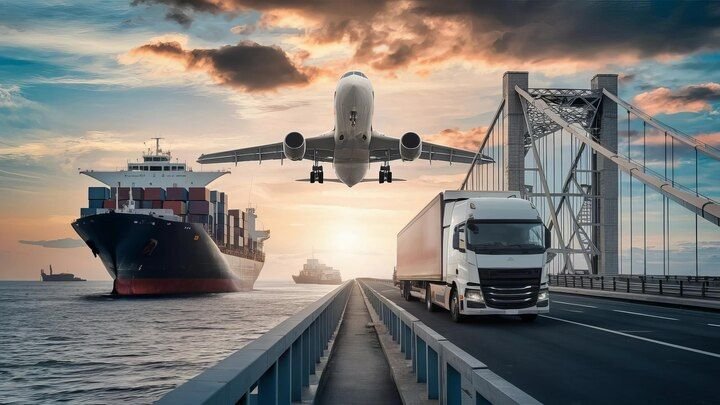
Every shipment is a risk. A truck can meet with an accident, a container can be damaged at port, or goods can be lost to theft or bad weather. If you move goods regularly, one such incident can wipe out your profit for months. This is where transit insurance steps in.
What Is Transit Insurance?
Transit insurance, also called goods-in-transit or marine cargo insurance, protects your goods against loss or damage while they move from one place to another. It can cover shipments by road, rail, air, or sea, from the moment goods leave the origin until they reach the destination.
What Does It Typically Cover?
Coverage depends on the policy, but commonly includes:
- Accidents involving the transporting vehicle
- Fire and explosion
- Theft and pilferage
- Natural calamities such as floods, storms, and earthquakes
- Damage during loading and unloading
- Sinking, collision, or derailment
What Is Usually Not Covered?
Always read the exclusions carefully. Typical ones are:
- Improper or inadequate packing
- Natural wear and tear, or inherent defects in goods
- Delay in delivery and resulting market loss
- Willful misconduct or negligence by the policyholder
- War and strikes, unless added as an extra cover
Types of Transit Insurance
- Inland transit insurance: for domestic movement by road, rail, or air.
- Marine cargo insurance: for imports and exports by sea or air. Policies often follow the Institute Cargo Clauses (A, B, and C), where Clause A gives the widest cover.
- Single-shipment vs. open policy: a single-shipment policy covers one consignment, while an open policy covers all shipments over a set period, which suits regular shippers.
Who Needs Transit Insurance?
- Manufacturers and traders sending goods to customers
- Exporters and importers
- E-commerce sellers and retailers
- Distributors and wholesalers
- Anyone shipping high-value or fragile items
A common misconception is that the transporter’s liability is enough. In reality, a carrier’s liability is usually limited and may not cover the full value of your goods, so your own cover is the safer choice.
How to Choose the Right Policy
- Declare the correct value: under-insurance can reduce your claim.
- Check the coverage type: “all risks” is broader than named-perils cover.
- Understand the exclusions: know what isn’t covered before you buy.
- Match the policy to your shipping pattern: open policies work well for frequent shipments.
- Review the claim process: a simple procedure and responsive insurer matter when you need them.
How to File a Claim
- Inform the insurer and carrier immediately.
- Do not dispose of the damaged goods.
- Collect the invoice, lorry receipt or bill of lading, packing list, and policy copy.
- Get a survey report or damage certificate where required.
- Submit the claim within the time limit mentioned in your policy.
Frequently Asked Questions
1.Is transit insurance mandatory?
Not for most domestic shipments, but exports and imports often require it, and it is strongly recommended for all valuable cargo.
2.Does the premium cost a lot?
It is usually a small percentage of the cargo value, which is minor compared with the loss it can prevent. The rate depends on goods, route, and mode of transport.
3.Can I insure just one shipment?
Yes, single-shipment policies are available.
Conclusion
Transit insurance is a small cost that protects your business from large, unexpected losses. Whether you ship once a month or every day, the right policy brings peace of mind and financial security.
Ready to protect your shipments? Contact us today for a customised transit insurance quote.
Disclaimer: This article is for general information only. Coverage and terms vary by insurer and policy, so please read your policy document carefully.